Cost Segregation When You Own Your Shop or Office Building
Tax Strategy
Most service business owners who own the building they operate out of are taking 39-year straight-line depreciation. A cost segregation study can reclassify part of the building basis (purchase price minus land) into 5/7/15-year property and pull those deductions forward. In a fictional $1.2M building-basis example with 25% reclassified and 100% bonus, the year-one deduction rises by about $292K, roughly $108K of federal tax deferred at a 37% top marginal rate.
Level editorial perspective; author Kenneth May, EA
If this is you
Fictional example: you bought the warehouse your HVAC business operates out of for $1.4M, with $200K allocated to land. Your CPA set up 39-year straight-line depreciation on the $1.2M building, giving you about $30,800 per year in deductions (land does not depreciate). A cost segregation study moves part of that building basis into 5-, 7-, and 15-year property. If qualified property was acquired and placed in service after January 19, 2025 and 25% is reclassified, your year-one deduction jumps to about $323K instead of $30,800, followed by about $23,100 per year on the remaining 39-year basis. If you bought the building earlier, the bonus rate is governed by the applicable acquisition and placed-in-service rules (including transition rules) for that property, such as 60% for most eligible property placed in service in 2024. It is called cost segregation, and compliance-only tax engagements miss it every year.
If you operate a service business (HVAC, plumbing, electrical, medical, dental, MedSpa, automotive shop, restaurant, gym, manufacturing, anything where you bought the commercial real estate you work out of) and your CPA hasn't done a cost segregation study on the property, you may be taking depreciation later than the law allows. Cost segregation mostly changes timing: deductions move earlier, later years get smaller deductions, and some benefit can be recaptured on sale.
Cost segregation is not an aggressive tax strategy. It's an engineering-based reclassification of the depreciable building basis of your commercial real estate. It is long-established practice, and the IRS publishes a Cost Segregation Audit Techniques Guide describing how examiners review studies. The Tax Cuts and Jobs Act of 2017 temporarily raised bonus depreciation to 100% and then phased it down. Public Law 119-21, commonly called the One Big Beautiful Bill Act, restored 100% bonus depreciation for qualified property acquired and placed in service after January 19, 2025.
Here's what it does, what it costs, why most service business owners miss it, and how to capture the deduction even on properties you've owned for years.
The default depreciation problem
Under standard tax accounting, when you buy commercial real estate, the IRS makes you depreciate the building over 39 years using straight-line method. Land is non-depreciable.
For a $1.4M purchase ($1.2M building, $200K land):
- Annual depreciation deduction: $1,200,000 / 39 years = $30,769/year
- At an assumed 27-37% federal marginal rate, that's roughly $8,300-$11,400/year of lower federal tax (mid-month convention ignored for simplicity)
For most service business owners, this feels fine. The tax bill goes down a little each year. Nobody questions it.
What 39-year depreciation misses: a $1.2M commercial building isn't actually 39-year property. It's a bundle of property classes:
- The structural shell (walls, roof, foundation): genuinely 39-year property
- Certain interior items that are not structural components (for example some carpet, removable cabinetry or decorative finishes): may be 5- or 7-year property, depending on the engineer's analysis
- Land improvements (parking lot, sidewalks, fencing, landscaping, exterior lighting): 15-year property
- Process-specific equipment built into the building (specialized electrical, HVAC for production space, dental water lines, etc.): 5-7 year property
When the IRS says "depreciate the whole thing as 39-year," you're stretching out depreciation that legally belongs in 5, 7, or 15-year buckets. Cost segregation fixes that.
What a cost seg study actually does
A cost segregation study is performed by a qualified engineer or specialist firm. The engineer reviews the property, the construction documents, and (for purchased properties) the appraisal and physical layout, and reclassifies the purchase price across the proper IRS asset classes.
Illustrative planning ranges for a service business commercial property (not measured medians; the actual split comes only from the engineer's study of your building):
| Asset Class | Illustrative % of building basis | Old Treatment | New Treatment |
|---|---|---|---|
| 5-year property | 8-15% | 39-year SL | 5-year MACRS w/ bonus |
| 7-year property | 5-10% | 39-year SL | 7-year MACRS w/ bonus |
| 15-year property | 8-15% | 39-year SL | 15-year MACRS w/ bonus |
| 39-year property | 60-79% | 39-year SL | 39-year SL (unchanged) |
The 5-, 7-, and 15-year property is now eligible for bonus depreciation, a special first-year deduction. Under Public Law 119-21 (commonly called the One Big Beautiful Bill Act), 100% bonus depreciation applies to qualified property acquired and placed in service after January 19, 2025. Property acquired or placed in service earlier uses the bonus rate governed by the applicable acquisition and placed-in-service rules (including transition rules) for that property, such as 60% for most eligible property placed in service in 2024, which matters for look-back studies on older buildings.
Fictional worked example used throughout this page: $1.4M purchase, $200K land, $1.2M building basis, 25% reclassified ($300K), property acquired and placed in service after January 19, 2025 so 100% bonus applies, and an owner who can use the full deduction at the 37% top federal marginal rate. Mid-month convention ignored for simplicity.
- Year-one deduction: $300,000 bonus + $900,000 / 39 ($23,077) = about $323,077, vs $30,769 under default treatment
- Incremental year-one deduction: about $292,308
- At 37%: about $108,154 lower year-one federal tax
- Sensitivity: at 20% reclassified the incremental deduction is about $233,846 (about $86,523 at 37%); at 30% it is about $350,769 (about $129,785 at 37%)
This is mostly timing. From year two, the remaining 39-year basis deducts about $23,077/year instead of $30,769, and recapture can apply on sale. Whether you can use the deduction this year also depends on your actual marginal rate, passive activity rules (including self-rental arrangements where a separate entity owns the building and leases it to the operating company), basis and at-risk limits, and whether your state conforms to federal bonus depreciation.
Why Operating Profit Beats W-2 Pay Under the 2026 $512K Cap
On the $1.2M warehouse above, if the building is validly grouped with a profitable HVAC business, that operating profit absorbs the $323K first-year deduction before the Excess Business Loss cap is ever tested (and even before operating profit, $323K is below the $512,000 married filing jointly cap, though above the $256,000 single cap). When you buy a larger headquarters or hold multiple properties, where your income comes from decides whether the $512,000 Excess Business Loss cap hits you.
Every cost segregation loss has to pass five IRS gates in order before it can reduce your tax bill:
- Basis: You need enough tax basis in the entity that owns the building. Partnership LLCs include your share of the mortgage, while S-corporations only count your stock basis plus direct shareholder loans.
- At-Risk: Your deduction is limited to your cash down payment plus recourse loans and qualified real estate bank financing.
- Passive Activity: Rental real estate is passive by default. When you validly group your operating company (OpCo) and building LLC (RealCo) and materially participate in the grouped business, the IRS treats your shop depreciation as an active deduction.
- Excess Business Loss ($512,000 Married / $256,000 Single for 2026): On Form 461, aggregate trade or business income (after passive and capital-gain rules, including operating business profit) absorbs your cost segregation loss dollar for dollar before the $512,000 cap is tested. W-2 wages (including S-Corp officer W-2 salary) do not count as business income on Form 461.
- Net Operating Loss Carryforward: Any loss capped at Gate 4 carries forward into Year 2 as a Net Operating Loss (NOL). In Year 2, it can offset up to 80% of your modified taxable income before the NOL deduction without hitting the $512,000 cap again.
To see how Gate 4 works on a larger headquarters purchase, compare two married taxpayers in 2026 who each make $1,000,000 and each generate a $1,000,000 non-passive cost segregation loss (using a flat 37% rate and assuming $1,000,000 of 2027 modified taxable income before the NOL deduction):
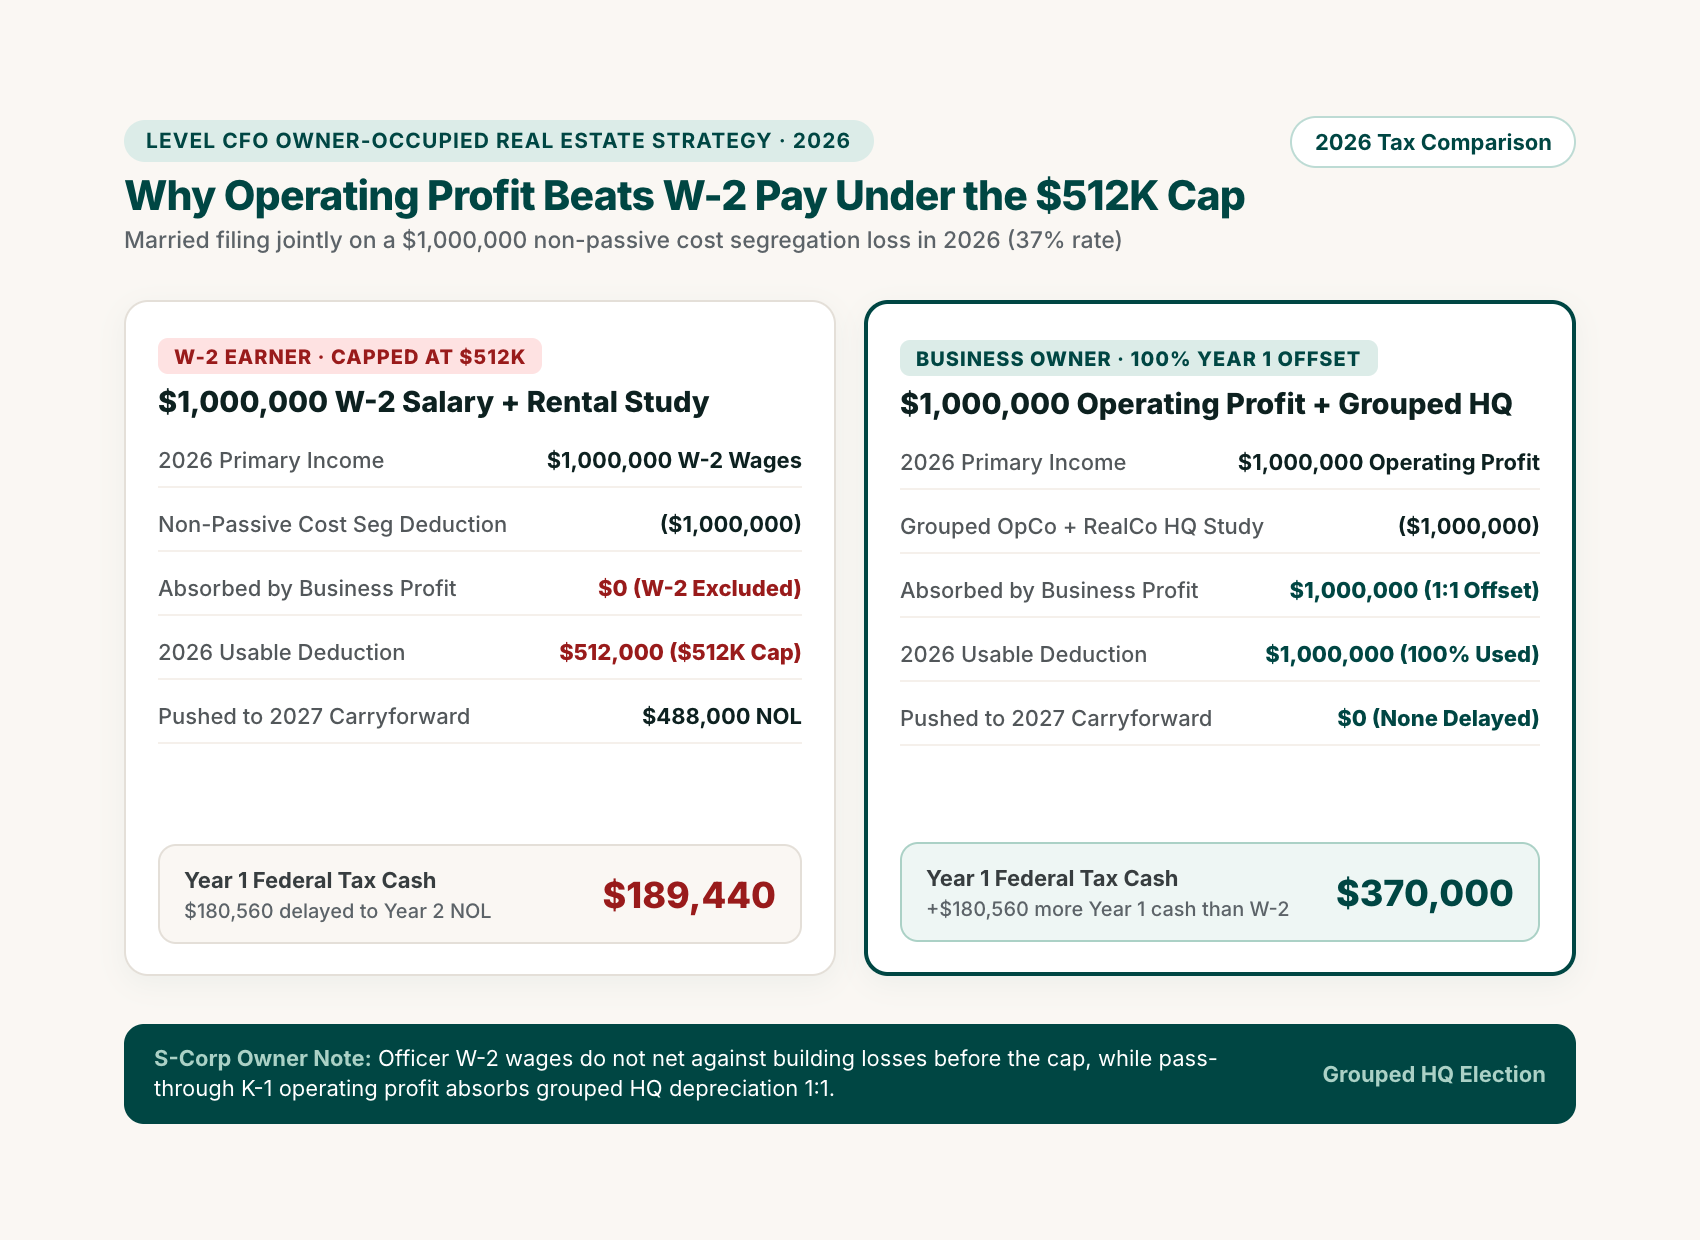
| 2026 Illustrative Comparison (Married Filing Jointly) | W-2 Executive ($1M W-2 Salary + Non-Passive STR / REPS Study) | Service Business Owner ($1M Active Operating Profit + Validly Grouped Shop/HQ Study) |
|---|---|---|
| Primary Income | $1,000,000 W-2 wages | $1,000,000 active operating profit |
| Non-Passive Cost Seg Loss | ($1,000,000) | ($1,000,000) |
| Absorbed by Business Income Before Cap | $0 (W-2 wages do not count as business income) | $1,000,000 (absorbed dollar for dollar) |
| Year 1 Usable Deduction (2026) | $512,000 (capped at the 2026 $512,000 limit) | $1,000,000 (100% used in Year 1) |
| Remaining 2026 Income Before Other Adjustments | $488,000 | $0 |
| Carried Forward to 2027 as an NOL | $488,000 (offsets up to 80% of 2027 modified taxable income before the NOL deduction, or $800,000 on $1M, so the full $488,000 is used in Year 2) | $0 |
Because the contractor earns operating profit, validly groups the self-rental warehouse with the operating company, and materially participates in the grouped activity, their $1,000,000 business profit absorbs the entire $1,000,000 depreciation loss before Gate 4 applies. The W-2 earner only uses $512,000 in Year 1 and carries the remaining $488,000 into Year 2. (For engineering details on all five gates and electing out of bonus depreciation by asset class, see FreeCostSeg's guide to the 2026 Excess Business Loss cap.)
Free benchmark review
See how your tax and cash plan benchmarks.
Start with a free conversation about your priorities. With agreed access to the relevant records, we compare your numbers with applicable benchmarks and identify what to review first.
The look-back rule: catch up on properties you've owned for years
Most service business owners assume cost segregation only works in the year you buy the building. That is not true.
If you bought that same $1.2M warehouse four years ago and depreciated the entire building over 39 years, you can still run a look-back cost segregation study today. Instead of amending old tax returns, your CPA files IRS Form 3115 with your current return to claim the missed prior-year depreciation as a net Section 481(a) adjustment (a negative adjustment generally reduces income in the year of change, whereas a positive adjustment generally has different timing).
How a look-back study works on that $1.2M warehouse:
- An engineer reviews the building as of your original purchase date and identifies $300K (25%) of shorter-life components ($120K of 5-year, $80K of 7-year, and $100K of 15-year property).
- Even in a conservative case where a valid election out of bonus depreciation was made for those classes, standard four-year MACRS depreciation on that $300K totals $185,022 ($99,264 on 5-year + $55,008 on 7-year + $30,750 on 15-year).
- Subtracting the $30,769 of slow 39-year depreciation you already took on that $300K leaves a one-time catch-up deduction of about $154,253 this year (worth about $57,074 in lower federal tax at a 37% rate).
- If the property qualified for 100% bonus depreciation in the year you placed it in service and no election out was made, the catch-up deduction rises to about $269,231 ($300,000 minus $30,769).
What a cost seg study costs
Illustrative planning ranges for service business commercial property (not measured from a stated sample; fees and results vary by firm, property and acquisition year):
| Property Type | Illustrative study fee | Illustrative 1st-year federal tax deferral | Independent illustrative scenario multiple |
|---|---|---|---|
| Single-tenant retail/office (under $1M) | $3,500 - $6,000 | $25K - $60K | 7-15x |
| Mid-size commercial ($1M-$3M) | $5,000 - $10,000 | $50K - $200K | 8-20x |
| Industrial/warehouse ($1M-$5M) | $5,000 - $12,000 | $80K - $300K | 10-25x |
| Medical office or dental ($1M-$3M) | $6,000 - $11,000 | $80K - $250K | 12-25x |
Specialty property types (medical, dental, restaurant) often have a higher percentage of qualifying assets because of process-specific equipment built into the structure.
The final column retains separate illustrative scenarios; it is not calculated from the fee and deferral range endpoints. A real multiple requires a paired study fee and tax effect for the same property. Get actual quotes rather than relying on these ranges. Compare the study fee to the after-tax value of the deferral (including smaller depreciation later and possible recapture on sale), not to the gross first-year tax reduction. In the fictional example above, a $7,500 fee against about $108,154 of year-one federal tax deferral is roughly 14x on a first-year basis, but that is a timing benefit, not a 14x permanent return.
What kinds of buildings are best for cost seg
Excellent candidates:
- Service business HQ with shop/warehouse space (HVAC, plumbing, electrical, automotive, manufacturing)
- Medical and dental offices (significant specialty MEP, dental water lines, X-ray rooms, patient finishes)
- MedSpa and aesthetic clinics (treatment rooms, lighting, specialty plumbing)
- Restaurants (kitchen equipment built into structure, exhaust systems, walk-in coolers)
- Gyms and fitness centers (specialty flooring, plumbing, locker rooms)
- Self-storage and mini-storage facilities (high % land improvements)
- Retail with significant fit-out (custom millwork, lighting, flooring)
Poor candidates:
- Residential rental property (27.5-year rules apply; it can still be a cost seg candidate, but it is outside this page's owner-occupied scope)
- Bare-shell offices with minimal fit-out
- Property purchased for under $300K (a screening example, not a categorical exclusion; compare the quoted fee with your modeled after-tax timing benefit). The separate $400K basis screen below is also illustrative, not an eligibility cutoff.
- Property where you plan to sell within 5 years (recapture rules can claw back the benefit)
The recapture trap (and how to plan around it)
Accelerated depreciation creates depreciation recapture exposure when you sell the property. Gain on 5- and 7-year personal property is generally recaptured as ordinary income (up to the 37% top rate) to the extent of depreciation taken. Gain attributable to straight-line depreciation on the building is generally taxed as unrecaptured Section 1250 gain at up to 25%, depreciation on real property in excess of straight line can be recaptured as ordinary income, and remaining gain is long-term capital gain. Have your tax preparer model the sale allocation.
For a property sold within 5-10 years, the recapture can erode much of the cost seg benefit. Before doing a study, ask:
- Will I own this property for at least 7-10 more years?
- If I sell, which assets qualify for a 1031 exchange and which generate taxable gain? Section 1031 covers qualifying real property, not personal property; the classification for an exchange needs its own analysis, so do not assume the study makes every recapture amount deferrable.
- Am I comfortable with the recapture math at sale?
For long-term holders, the deferral value of accelerated depreciation often exceeds the recapture cost, but that depends on your marginal rate now versus at sale, so model it rather than assume it. For owners likely to sell within 5 years, run the math carefully before the study.
For deeper engineering background on cost segregation studies, see FreeCostSeg, our partner site dedicated to the engineering and IRS-audit mechanics of cost segregation. For a complete real estate tax library covering investor strategies, REPS, STR loophole, and 1031 exchanges, see Overline.
What to do this quarter
If you own commercial real estate that your service business operates out of:
Action 1: Pull your depreciation schedule from your most recent tax return. If you see "39 years SL" with no allocations to 5/7/15-year property, you have not had a cost seg study done.
Action 2: Calculate your purchase price minus land value. As an illustrative screening threshold (not a rule), a building basis over about $400K is where a study is often worth pricing; confirm with an actual fee quote and your own marginal rate.
Action 3: Get a free preliminary estimate from a cost seg specialist firm. Some firms offer free estimates of the year-one deduction and savings before you commit. The numbers either work or they don't, no obligation either way.
Action 4: If the math works, schedule the study before year-end. The catch-up is claimed for the year of change for which Form 3115 is filed with a timely return (including extensions), and for new purchases in the year the property is placed in service. Confirm filing timing with your tax preparer.
The tax code allows this. It is easy to skip because it requires coordinating an engineering study with your tax preparer. The size of the benefit depends on your building basis, the reclassified share, the bonus rate governed by your property's acquisition and placed-in-service rules, and whether you can use the deduction now; the fictional example above shows how to run your own numbers.
Get a cost seg estimate in 2 minutes or book a free 30-min audit. We'll review your property situation and refer you to a vetted engineer if the math works.
CPA & Tax Preparer Technical Reference
What to Hand Your CPA (Statutory Checklist for OpCo + RealCo Grouping & Form 3115 Look-Back Studies):
- Gate 1 & 2 (Basis & At-Risk): IRC Section 704(d) (partner outside basis including allocable partnership nonrecourse debt under Section 752), Section 1366(d) (S-corp shareholder stock basis plus direct shareholder loan basis), Section 167(c), and Section 465(b)(6) qualified nonrecourse real estate financing (Form 6198).
- Gate 3 (Self-Rental Grouping vs. REPS/STR): Under Treas. Reg. 1.469-2(f)(6), net rental income from property leased to an activity in which the owner materially participates is non-passive, while net rental losses generally remain passive unless the activity is validly grouped with the operating business or the owner otherwise qualifies for non-passive rental treatment (such as REPS with material participation in the rental activity). Under Treas. Reg. 1.469-4(c) and Treas. Reg. 1.469-4(d)(1)(i), an operating company (OpCo) and building entity (RealCo) that form an appropriate economic unit may be grouped when one activity is insubstantial in relation to the other or when each owner holds the same proportionate ownership interest in both entities, provided the owner materially participates in the grouped activity and files the required disclosure under Rev. Proc. 2010-13. By contrast, third-party rental investors clear Gate 3 via REPS (IRC Section 469(c)(7), requiring more than 750 hours and more than 50% of personal services in real property trades or businesses with material participation, plus material participation in each rental activity or in the combined rental activity after a valid Reg. 1.469-9(g) aggregation election) or the STR exception (Treas. Reg. 1.469-1T(e)(3)(ii)(A), requiring an average customer use of 7 days or less plus material participation such as more than 100 hours and not less than any other individual under Reg. 1.469-5T(a)(3)).
- Gate 4 & 5 (Form 461 & NOL Carryforward): Under IRC Section 461(l)(3)(A), aggregate trade or business deductions net against aggregate trade or business gross income/gains (after passive-loss and Section 461(l)(3)(C) business capital gain limits) before testing the 2026 threshold under Section 461(l)(3)(A)(ii)(II), Section 461(l)(3)(B) (cost-of-living adjustment), and Rev. Proc. 2025-32 sec. 4.31 ($512,000 married filing jointly / $256,000 single). Employee W-2 wages (including S-corp officer W-2 salary) are excluded from trade or business income under the concluding flush language of Section 461(l)(3)(A). Disallowed losses convert to a Section 172 NOL carryforward under Section 461(l)(2) and offset up to 80% of modified taxable income before the NOL deduction (computed without NOL, Section 199A, and Section 250 deductions) under Section 172(a)(2), while class-by-class bonus opt-outs use Section 168(k)(7) (which applies to all qualified property in that MACRS class placed in service by that taxpayer during the taxable year).
- Form 3115 Method Change & Section 481(a) Mechanics: Look-back studies use the IRS automatic accounting-method change procedures (Rev. Proc. 99-49 was an early version and has since been superseded; confirm the current automatic-change revenue procedure and change number in IRS Publication 946 and current IRB guidance). An eligible negative net Section 481(a) adjustment (missed depreciation) is generally deducted in full in the year of change, whereas a positive adjustment has different timing. The no-bonus look-back example above uses standard MACRS half-year table rates (ignoring mid-month convention on the 39-year portion for simplicity) and assumes a valid election out of bonus depreciation under Section 168(k)(7) was made on the original return. For eligible property placed in service in 2022, 100% bonus generally belonged in allowable depreciation unless a timely election out applied. An automatic Form 3115 corrects an impermissible recovery period; it cannot generally be used to revoke or reverse a valid prior Section 168(k)(7) election out of bonus depreciation. A one-year correction versus an established accounting method (two or more returns) also governs whether an amended return or Form 3115 applies.
Related reading
Free Excel & CSV Workpapers (No Email Required)
Download the contractor accounting & QuickBooks tie-out pack
Built from real-world contractor monthly close controls rather than generic spreadsheet formulas, including our 3-account clearing model (Invoice Sync Clearing, Card Payout Clearing, and Payroll Clearing), uninstalled materials cutoff, WIP-to-balance-sheet tie-out, and surety working-capital haircut schedules:
+ Show 7 more specialist CSV workpapers (WH-347 Payroll, QoE EBITDA, 13-Week Cash Flow, Service Agreements)
Free profit audit
Have us reach out for a free audit
Drop your work email and our team will reach out within a few business hours to benchmark your books against 2,200+ contractors in the research universe.
Related reads
Tax Strategy
Foreign Subsidiary Tax & Accounting: Form 5471 & 5472 Guide
How Delaware C-Corps with foreign subsidiaries handle intercompany IP and R&D agreements, Section 174 foreign R&D, and IRS Form 5471 and 5472 filings.
Tax Strategy
179D Energy Deduction in 2026: Post-Deadline Evidence and Cost-Basis Checks for Contractor-Owned Buildings
Check 179D eligibility after June 2026: construction-start evidence, energy certification, deduction limits and cost-segregation basis adjustments.
Tax Strategy
2026 QBI Deduction for Doctors, Lawyers and Consultants: SSTB Phaseout and Planning Limits
2026 Section 199A SSTB phaseout depends on taxable income and filing status. Review retirement contributions, common-ownership limits and entity choices before assuming an equipment or real-estate LLC restores the deduction.
About the author
Kenneth May
Partner, Tax Strategy
Enrolled Agent and tax planning specialist with 45+ years of practice. Owner of B A Services Inc. (Standish, Michigan), focused on tax strategy for medical, legal, real estate, and e-commerce businesses in the $1M-$5M revenue band. As an EA, federally licensed to represent taxpayers before the IRS in all 50 states. Specializes in entity structuring, strategic tax deferral, R&D and other under-claimed credits, and retirement-plan design for owner-operators. Brings the tax-strategy lens to Level's content, the part most fractional CFOs ignore.
LinkedIn