Why AI Finance Projects Fail in Service Businesses
LEVEL AI FINANCE THESIS
A balanced balance sheet only proves the bank feed cleared, not that a single job made money
Sam Yang, Level
The short answer
A balanced QuickBooks balance sheet only proves that cash cleared your bank feed and debits equaled credits. Across 315,393 budgeted jobs from 1,391 contractors in Level's dataset, 40% exceed budgeted labor hours, and unassisted AI models average 54.1% accuracy (capping at 71%) on 100 real month-end close checks. Real job-cost control requires weekly field-to-ledger reconciliation across dispatch, payroll, supplier POs, and WIP.
Key takeaways
- Bank-feed tools only see cash clearing: Categorizing bank transactions cannot tell you whether a closed ticket was billed or which crew lost money on callbacks.
- Clean tax books still hide six-figure leaks: In an anonymized $8.4M contractor diagnostic where every bank account reconciled to the penny, field-to-ledger audits uncovered $432,000 in annual profit and billing leaks plus $500,000 in unadjusted WIP distortion.
- PE rollups multiply the blind spot: Consolidating five acquired contractor QuickBooks files into a portfolio dashboard without standardizing field-to-ledger rules makes the sloppiest branch look like the highest-margin performer.
See whether your books are benchmark-ready.
Compare your margins and cash flow against industry benchmarks or view flat-rate CFO & bookkeeping pricing.
Why a "Clean" QuickBooks Balance Sheet Still Lies to Contractors
Every week, a $3M to $25M HVAC, plumbing, electrical, or roofing owner tells us the same thing: "Our CPA says our QuickBooks is clean and every bank account is reconciled, so why is cash so tight?"
A reconciled bank feed only proves two things:
- Cash entered or left your checking account and credit cards.
- Every transaction was dropped into a tax bucket so debits equal credits.
 Why a Clean QuickBooks File Still Hides Job-Cost LeaksClick to expand
In a trade business, profit is decided in the field before a transaction ever hits the bank feed:
- Dispatch: A technician closes an after-hours repair ticket in ServiceTitan, BuildOps, Jobber, or Housecall Pro.
- Payroll: A crew logs four hours of unbilled warranty rework in Gusto or ADP.
- Purchasing: A project manager pulls $14,000 of copper and fittings at Ferguson on a job PO.
- Progress Billing: A commercial GC approves a 40% draw while field work is 65% complete.
Until those four operational records are tied line by line to QuickBooks, a balanced ledger is just a tax-filing summary pretending to be job costing.
Three Levels of Financial Truth: Bank Feeds vs. Templates vs. Field Ground Truth
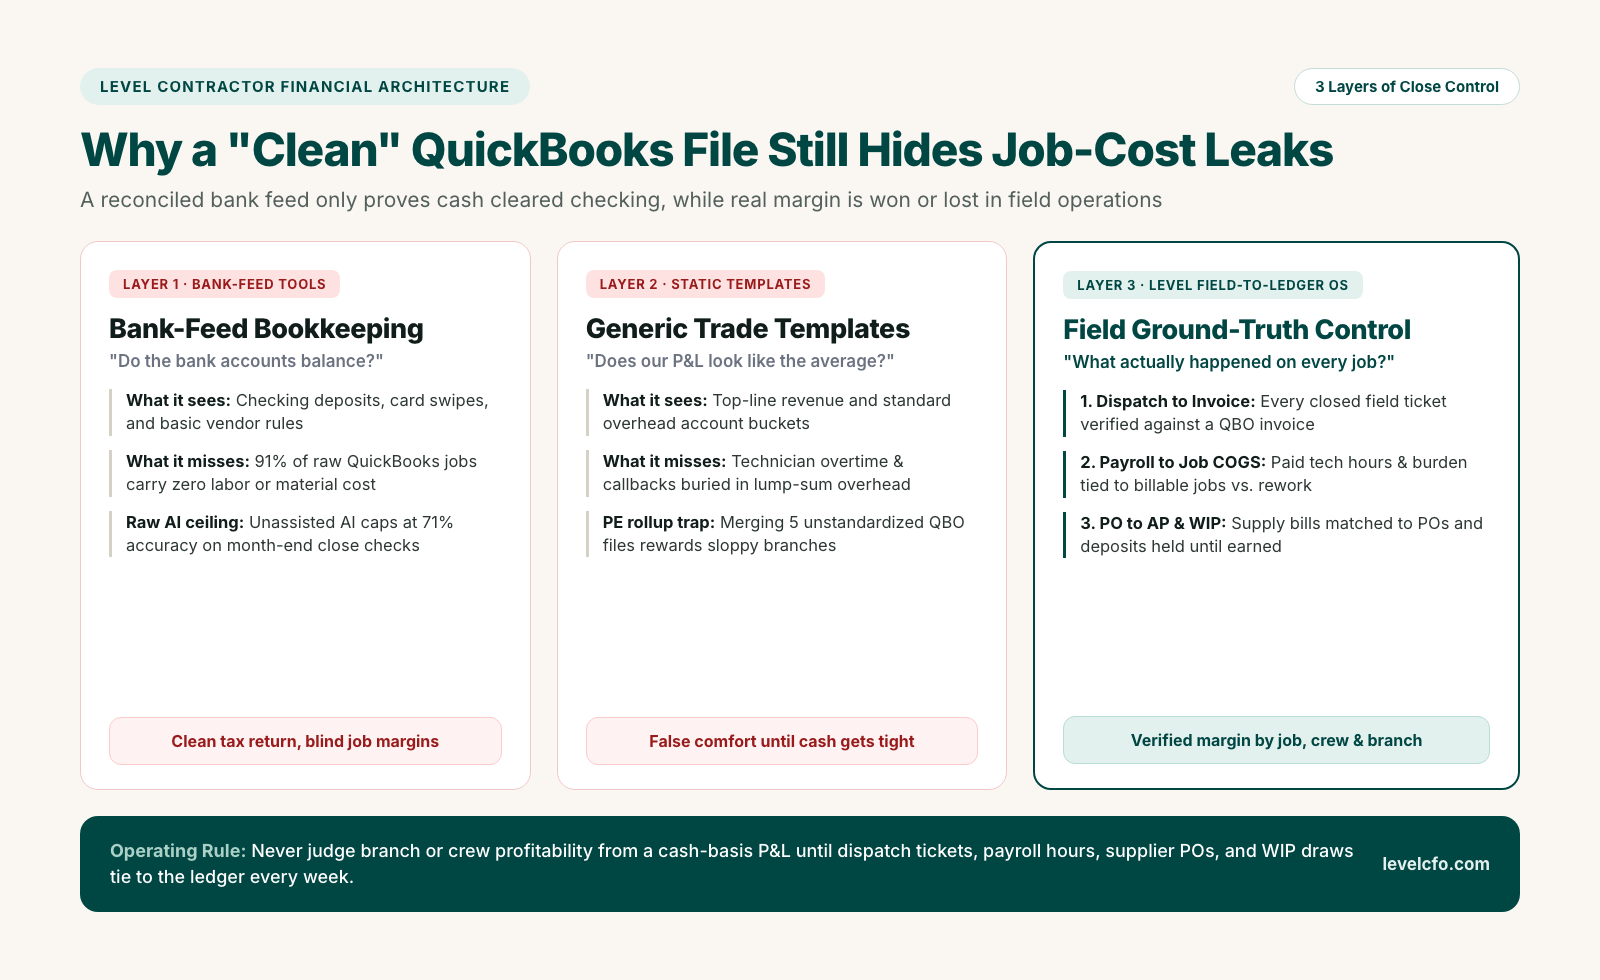
When we audit contractor QuickBooks takeovers and test AI models against our 100-check month-end close benchmark, every setup falls into one of the three layers shown above:
- Layer 1 (Bank-Feed Bookkeeping): Auto-categorizes bank deposits and card swipes faster while leaving job-level technician labor and supplier POs unlinked to jobs (where 40% of 315,393 budgeted jobs overrun hours). Unassisted AI models average 54.1% accuracy and cap at 71% here because operational evidence lives outside the bank feed.
- Layer 2 (Generic Trade Templates): Maps standard P&L buckets against industry averages, but misses technician wages, overtime, and warranty callbacks buried inside lump-sum G&A overhead.
- Layer 3 (Field-to-Ledger Control): Ties every closed dispatch ticket, paid technician hour, supply-house PO, and commercial progress draw directly to QuickBooks every week so realized margin is visible by job, crew, and branch.
Most off-the-shelf automation tools live entirely in Layer 1. They categorize bank feeds faster while leaving field payroll in overhead and progress draws disconnected from field completion.
Free benchmark review
See whether your books are benchmark-ready.
Start with a free conversation about your priorities. With agreed access to the relevant records, we compare your numbers with applicable benchmarks and identify what to review first.
Inside an $8.4M Contractor's "Balanced" QuickBooks File: $432,000 in Leaks
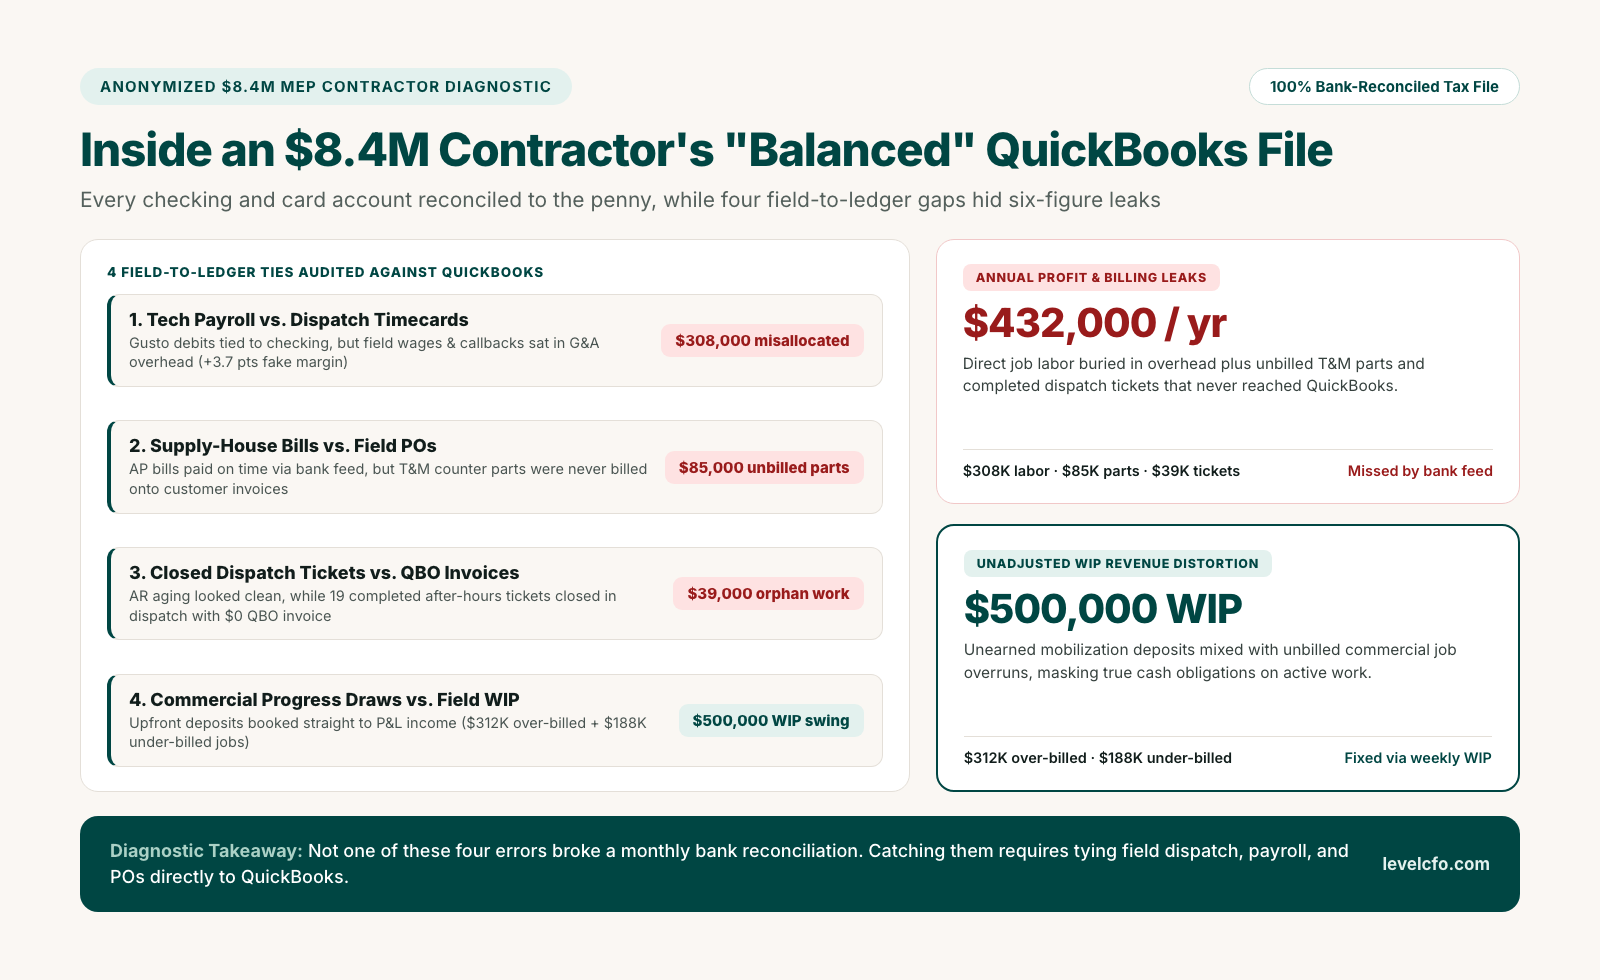
Here is an anonymized composite from our $8.4M commercial and residential MEP contractor takeovers. Before we touched the file, every bank and credit card account was reconciled to the penny.
 Inside an $8.4M Contractor's Balanced QuickBooks FileClick to expand
Cross-checking QuickBooks against ServiceTitan dispatch tickets, Gusto timecards, supply-house bills, and active commercial jobs exposed $432,000 in annual profit and billing leaks alongside $500,000 in unadjusted WIP revenue distortion:
- $308,000 in misallocated field labor: Gusto payroll debits matched checking to the cent, but technician wages, overtime, and callbacks sat in lump-sum G&A overhead instead of job COGS, inflating reported gross margin by 3.7 points.
- $85,000 in unbilled T&M parts and $39,000 in orphan tickets: Supply-house counter parts pulled for T&M service calls were expensed to general materials without customer markup, and 19 completed after-hours dispatch tickets closed with zero invoice ever created in QuickBooks.
- $500,000 in unadjusted WIP and customer deposits: $312,000 of upfront customer deposits on unstarted jobs and $188,000 of unbilled work on overrunning commercial projects sat unadjusted on the P&L.
Not one of those errors broke a bank reconciliation. Every single one required comparing QuickBooks against operational records outside the ledger.
Why PE Rollups and Multi-Shop Operators Hit This Wall First
If you are an operating partner or CFO rolling up five $4M to $15M HVAC, plumbing, or roofing companies, plugging five unstandardized QuickBooks files into a BI dashboard creates an immediate trap:
- Shop A maps every technician hour, payroll tax dollar, and warranty callback into job COGS. Its reported gross margin is 38%.
- Shop B dumps $300,000 of technician overtime, drive time, and callbacks into general overhead and books customer deposits as revenue on day one. Its reported gross margin is 54%.
On a consolidated rollup dashboard, Shop B looks like your star branch and Shop A looks like it has a pricing problem. In reality, Shop A is generating cash and Shop B is underpricing installs while burning through customer deposits.
Before a multi-branch operator or PE platform can compare unit economics across branches, all entities must run on the same weekly field-to-ledger rules.
The Four Weekly Field-to-Ledger Reconciliation Loops
To turn QuickBooks from a rear-view tax ledger into an operating scoreboard, run four weekly AI Accounting Reconciliation Controls between your field software and your general ledger:
- Dispatch-to-Invoice Completeness: Every job marked complete in ServiceTitan, BuildOps, Jobber, or Housecall Pro must match a posted QuickBooks invoice ID or carry a signed-off warranty or membership zero-dollar code before Friday close.
- Gross Payroll-to-Job COGS Mapping: Every paid technician hour in Gusto, ADP, or Rippling must reconcile to clocked field hours across billable jobs, unbilled travel, shop time, and warranty callbacks so direct labor never hides in overhead.
- PO-to-AP Bill & T&M Markup Check: Every supply-house bill from Ferguson, Johnstone, or ABC Supply must match a field PO and job number before payment, and any T&M material cost must verify a corresponding billable line item on the customer invoice.
- Earned Revenue-to-WIP Cutoff: Every upfront deposit and commercial progress draw must be checked against field percent-complete (actual labor and material cost incurred divided by updated total estimated cost). Cash collected ahead of mobilization stays in an unearned deposit liability account until work starts.
Run a Field-to-Ledger Profit & Cash Diagnostic on Your Books
You do not need a six-month ERP overhaul to see where margin is leaking. During a QuickBooks cleanup and field-to-ledger diagnostic using read-only accountant access, one payroll register export, and your last 90 days of closed dispatch tickets, we measure three numbers right away:
- Uncosted Job Rate: What share of closed QuickBooks invoices carry zero direct labor or material cost.
- Orphan Ticket Leak: How many completed jobs in ServiceTitan, BuildOps, Jobber, or Housecall Pro never generated a QuickBooks invoice.
- True Burdened Gross Margin: What your install, service agreement, and T&M margins actually look like once field payroll and callbacks are moved out of overhead.
Frequently Asked Questions
Because most contractor QuickBooks files leave field technician wages, payroll taxes, truck costs, or supply-house bills sitting in general overhead instead of matching them to individual jobs, and book upfront customer deposits directly into income before the crew starts the work. Your top-line gross margin looks artificially high while unbilled overruns and upcoming crew payroll drain cash.
No. A bank feed only sees when cash clears checking or a credit card is swiped. It cannot see which technician worked on which rooftop unit, whether a Ferguson supply-house bill belongs to a quoted flat-rate install or a billable T&M repair, or what percentage of a commercial project is complete in the field. Across our 100-check month-end close evaluation, unassisted AI models topped out at 71% accuracy because those operational triggers live outside the bank feed.
Standardize the four weekly field-to-ledger reconciliation rules (dispatch-to-invoice completeness, gross payroll-to-job COGS mapping, PO-to-AP bill matching, and earned-revenue WIP cutoffs) before consolidating P&Ls across portfolio companies. Otherwise, branches that dump direct labor into overhead will appear to have the highest gross margin in the portfolio.
Sources and method
Accounting software integration guides and Agentic Accounting & Month-End Close Benchmark. Case-study bridge figures ($8.4M revenue, $432,000 annual leaks, $500,000 WIP swing) represent an anonymized illustrative composite from Level contractor financial takeovers; benchmark figures (40% of 315,393 budgeted contractor jobs exceeding budgeted labor hours across 1,391 companies, and 54.1% mean / 71% ceiling unassisted AI month-end close accuracy across 27 foundation models) come from Level's published datasets.
Sample reconciliation worksheet and downloadable CSV
Financial evidence in practice
Why can an AI finance project fail even when the books balance?
A balanced ledger can still miss what happened on the job. AI can organize documents and candidate matches, but complete field records, arithmetic, job-cost mapping and controller sign-off still need explicit rules.
How to verify
- Define the exact operating question and required source records.
- Tie dispatch tickets, payroll hours and supplier bills by ID before summarizing.
- Quarantine missing check images or unmatched tickets for human review.
- Verify reconciled balances in the ledger before closing the week.
Illustrative example: Linked records with missing costs
All three fictional IDs link, giving 100% linkage. One has no cost evidence. Perfect linkage does not establish profit completeness.
View sample check output
{
  "fictional": true,
  "unit": "USD cents",
  "id": "report-population",
  "linkagePct": 100,
  "missingCostIds": [
    "C"
  ],
  "profitAvailable": false,
  "limitation": "This is teaching arithmetic from supplied invented inputs, not source authenticity, financial assurance or authority to post."
}Reviewed 2026-10-06. Level financial-control guidance, with visibly fictional teaching examples. Illustrative scenario only, not a customer result or industry benchmark.Read this content revision history
Continue with the related financial decision →Additional reconciliation examples
Paid, operational and productive labor hours
Fictional $4,800 payroll over 160 paid hours is $30 per paid hour; over 120 operational hours it is $40. With $1,200 allocated overhead and 80 productive hours, the estimating basis is $75 per productive hour. These rates answer different questions. A separate fictional operational budget of 100 hours and $6,000 payroll gives 20% more actual operational hours and 20% lower payroll, with a lower payroll rate on the same operational-hour basis.
Free Excel & CSV Workpapers (No Email Required)
Download the contractor accounting & QuickBooks tie-out pack
Built from real contractor monthly close controls. Covers our 3-account clearing model, uninstalled materials cutoff, WIP balance-sheet tie-outs, plus surety working-capital haircut schedules:
+ Show 7 more specialist CSV workpapers (WH-347 Payroll, QoE EBITDA, 13-Week Cash Flow, Service Agreements)
Free profit audit
Have us reach out for a free audit
Drop your work email and our team will reach out within a few business hours to benchmark your books against 2,200+ contractors in the research universe.
Related reads
Operations
Why Your Field Software Numbers Don't Match Your Accounting
Reconcile field hours, invoices, recognized revenue, and job costs. Billing capture: 97.1% median, 66.9% bottom decile (963 companies).
Operations
The AI Inbox: Emailed Reports as Finance Pipelines
Asking for a report by email does not mean you have received and saved it. Track delivery, original attachment, parsing and review separately, preserving changed versions.
Operations
The API Is Not Enough for Finance Automation
Use APIs for supported records. Add native reports or permitted browser collection for verified gaps, then compare identities, dates and costs.
About the author
Sam Yang
Founder & CEO
Founder of Level, the always-on finance team for contractors, service businesses, and ecommerce brands. Ex-CFO across trades, SaaS, and service businesses. 4 years as Director of Growth Product at BuildOps, building financial tooling used by 1,000+ commercial contractors. Four years in PE and investment banking rolling up and acquiring service businesses, $2.5B in total transactions including M&A and IPOs. Stanford MBA, Brown undergrad. The Level founding team's analysis of 2,200+ contractors ($13.25B in job revenue) across operating, private-equity, and CFO roles anchors the Level Index benchmark research.
LinkedIn