T&M Job Controls That Protect Your Margin
From Level's proprietary contractor research
T&M work needs a documented scope boundary, whether established by the contract, work order or acknowledged estimate. In one individual Level review, fewer than one in ten quote records were marked as formally sent; outside-channel communication was not measured.
One Level quote review at a single contractor; not a market prevalence estimate
The Most Dangerous Job Type in Contracting
Time and materials work can protect a contractor from some fixed-price overruns. You bill contract-eligible hours and apply the agreed material markup. Not-to-exceed prices, warranty exclusions and scope-approval terms still limit what you can bill.
In practice, T&M is where margin goes to die.
After reviewing contractor financials across hundreds of companies, in private equity, building financial products for commercial contractors, and now at Level, T&M jobs are where I most often see margin leak and the widest gaps between expected and actual cost. That is a review observation, not a measured comparison. Level has not published a gross-margin distribution that separates T&M from fixed-price jobs, so this page does not assign T&M a margin range. The reason for the leak usually isn't the pricing model. It's the absence of controls.
The Small Quote That Became a Much Larger Invoice
One T&M job from an individual Level financial review shows the mechanism: a small quoted service visit became a much larger invoice, with no documented change order or customer acknowledgment in the job record. The company figures stay qualitative. The underlying job file is not published here, so read it as one review observation, not a typical result or an industry rate.
No updated estimate, scope change form or customer acknowledgment appears in the job record. The tech just kept working. The office just kept booking hours. And by the time the invoice went out, it was too late for anyone to push back, the work was done.
This is an extreme case. Check whether the same control gap exists elsewhere in your own records. In one individual Level review, fewer than one in ten quote records were marked as formally sent to the customer. Most had no sent status in the system. Some of those prices may have been shared by phone or outside the software, so the figure measures a documentation gap. An absent software send flag alone does not prove that no scope or price was acknowledged through a contract, email or work order. Reconcile those channels before classifying an actual control failure. One contractor's records are not a market prevalence estimate.
Where no scope or price was acknowledged through any channel, T&M can become a blank check. The documentation review establishes whether that condition actually exists.
The Variance Data
Budget-to-actual on labor hours shows why in-job controls matter. This dataset covers all job types with both budgeted and actual hours, not a T&M-only cut. Across 315,393 jobs from 1,391 contractors, measured as actual hours divided by budgeted hours:
| Statistic | Actual as % of budget | Interpretation |
|---|---|---|
| P25 | 70.1% | Used well fewer hours than booked |
| Median | 99.4% | On budget |
| Mean | 119% | Pulled up by the overrun tail |
| P75 | 131.1% | Meaningfully over |
| Jobs past 150% of budget | 18.3% | Where the mean comes from |
The median job lands on budget, which sounds like a solved problem, and that is exactly the trap. The mean sits at 119% because 40% of jobs exceed their hour budget and 18.3% run past 150% of it. Individual company reviews can look worse. The earlier edition described extreme individual-company reviews with actual costs several times budget. Those unpublished cases are not a measured rate or a reason to equate the hours distribution with cost overruns. In your own data, test hours, wage mix, materials, scope and budget revisions separately.
If your own jobs show this pattern across many jobs, investigate the estimating and change-control process rather than treating it as one bad estimate. The cross-company hours distribution does not establish why your jobs ran over or whether materials, scope changes or execution caused the gap.
Why T&M Jobs Blow Up
1. No Customer-Facing Estimate
The biggest single control failure. If the customer never sees a number, they can't approve a number. And if there's no approved number, there's no scope boundary.
The fix: Send every T&M estimate to the customer before work begins. Even if it says "estimated range: $2,000-$5,000." Even if you disclaim it as an estimate. The act of sending a number creates a documented expectation. When the scope changes, you have a reference point: "The original estimate was $3,000. The additional work will be approximately $4,500. Do you want to proceed?"
In one individual review, fewer than one in ten quote records were marked as sent to customers. The rest had no sent status in the system. That is the majority of reviewed quote records without a sent status, not a verified count of jobs without customer approval.
2. No Scope Change Authorization
On a fixed-price job, scope creep is obvious: the work exceeds the contract, and you issue a change order. On T&M, extra work can look billable because the price follows time and materials. The contract can still set a scope boundary, authorization requirement or not-to-exceed cap. Review those terms before assuming the extra work is collectible.
The fix: Define a scope boundary even on T&M work. The original dispatch or work order describes what the tech is there to do. Anything beyond that scope requires a call to the customer before the work happens, documented in the system. "We found an additional issue. The repair will add approximately 3 hours and $800 in parts. Shall we proceed?"
The contractors who do this well make it a dispatcher or PM function, not a tech decision. The tech identifies the additional scope. The PM calls the customer. The approval is logged. The work proceeds.
3. No Real-Time Budget Tracking
On a T&M job, "budget" often means nothing, because the contractor's internal estimate is the only reference, and nobody checks actual costs against it until the invoice goes out (if then).
The fix: Set an internal cost-alert threshold for every T&M job, separate from any customer not-to-exceed price. For a fictional $3,000 internal cost budget, when actual and committed costs hit 80% ($2,400), the system flags the PM. The PM reviews: is the work almost done, or have we burned 80% of the budget on 40% of the scope? If the latter, stop and reassess before continuing.
The labor-hours data is clear on this: across 315,393 jobs with both budgeted and actual hours, 40% exceeded budgeted labor hours, and 18.3% exceeded 150% of budget. Those are not all scope failures, but they show why actual-versus-budget review belongs inside the job, not only after closeout.
4. Unbilled Hours
The other side of T&M margin erosion is job-logged hours that never reach an invoice. The median company captures 97.1% of hours logged on jobs, while the bottom quartile captures 89.2% or less and the bottom decile is at or below 66.9%. This is billing capture, not paid-hour utilization.
Fictional scenario: a crew records 20,000 job hours per year at a $150 customer rate. Capturing 76% instead of 97% is a 21-point gap, or 4,200 hours, which creates a $630K potential billing difference (4,200 × $150). That is billed revenue, not gross profit and not collected cash. It does not prove the full amount is recoverable (some write-offs are legitimate warranty or callback time), and it does not include travel or administrative hours that were never logged on jobs. The 76% is a scenario input, not a benchmark point. The measured lower quartile is 89.2% and the 10th-percentile boundary is 66.9%.
The fix: Audit billing capture monthly by technician and job. Investigate job-logged time that is absent from the invoice, coded to warranty, written off, or billed at a different rate. Calculate paid-hour utilization separately when diagnosing travel, administration, training, or idle time.
Free benchmark review
See how your margins benchmark.
We compare your jobs, crews, and service lines against real margin data, then show which gaps deserve the free audit.
The Five T&M Controls That Actually Work
Control 1: The Upfront Estimate (Always Send It)
Even on T&M work, send the customer a written estimate before dispatching. Include:
- Estimated labor hours and rate
- Estimated materials/parts
- Total estimated range (low-high)
- Clear statement: "This is an estimate. Actual charges will be based on time and materials used. We'll contact you if the scope changes significantly."
Treat 10 minutes as a planning allowance for preparing the estimate, not a measured guarantee of 10 hours of disputes avoided.
Control 2: The $500 Rule
Illustrative control: any scope addition exceeding $500 in estimated customer charges requires customer approval before the work is performed. Set the threshold for your own contract and job size. Use the change-authorization method your contract requires; an internal note records a phone approval but may not substitute for a required signed change order.
The tech calls the office. The office calls the customer. The approval is documented in the form your contract requires: a signed change order where required, or an accepted email, text or other method where permitted. An internal system note retains the record but does not replace required customer authorization. Then the work proceeds.
Pick your threshold. $500 is a starting point. For commercial work, $1,000 or $2,500 might be appropriate. The point is having a line that triggers a conversation rather than silent cost accumulation.
Control 3: Budget Alert at 80%
When a T&M job hits 80% of its internal cost estimate, the system notifies the PM. The PM has two questions to answer:
- Is the original scope 80%+ complete? If yes, proceed, the job is tracking to plan.
- Is the original scope less than 80% complete? If yes, stop. The job is going over. Reassess scope, contact the customer, get approval for the overage before continuing.
Do not treat the fictional $3,000 customer estimate in the script above as a $3,000 cost budget: price and cost are different. An alert against the approved customer not-to-exceed price uses projected customer charges; an internal cost alert uses the separate estimated cost.
Control 4: Daily Time Validation
Every tech's time entries are reviewed daily (or at shift end) by a dispatcher or office admin. Not for micromanagement. For accuracy:
- Is the time logged against the correct job?
- Are all hours accounted for (start to end of shift)?
- Is there non-billable time that should be billable, or vice versa?
Daily validation is one control that can improve the completeness of job time and invoices. In the fictional 20,000-job-hour scenario above, the difference between 76% and 97% billing capture is $630K at a $150 customer rate. The data does not prove daily review alone causes that gap.
Control 5: Post-Job Cost Review
Every T&M job over $5,000 gets a 5-minute post-job review: actual cost vs. estimate, any scope changes, any unbilled hours. This isn't a lengthy audit. It's a PM spending 5 minutes with the final numbers to ask: "Did this job go as expected? If not, why?"
Over time, this review feeds your estimating accuracy. If T&M estimates are consistently 30% under actual, your estimators are pricing too low, and your customers are getting sticker shock on invoices. If estimates are consistently 50% over actual, you're scaring away work with inflated quotes.
A starting planning target (an editorial assumption, not a measured Level benchmark): estimates within 20% of actual on at least 70% of jobs. Track it on your own closed T&M jobs. If you're not there, the estimating process needs calibration.
T&M vs. Fixed Price: When to Switch
The flat rate vs. T&M debate is ultimately about risk allocation. T&M puts the cost risk on the customer. Fixed price puts it on the contractor.
Shift to fixed price when:
- The scope is well-defined and repeatable (standard equipment changeouts, routine PM visits)
- You have enough historical data to estimate accurately (100+ similar jobs completed)
- The customer demands cost certainty (many commercial clients won't accept open-ended T&M)
Stay on T&M when:
- The scope is genuinely unknown (diagnostic work, emergency repairs, exploratory troubleshooting)
- The job involves old or unusual equipment where parts availability is uncertain
- The customer relationship supports transparent billing (long-term service agreement customers)
The hybrid approach works for many contractors: T&M for the diagnostic phase (with a not-to-exceed cap), then a fixed-price quote for the repair once the scope is defined. This gives the customer cost certainty for the bulk of the work while protecting the contractor from open-ended diagnostic time.
The Labor vs. Materials Split
One more data point that matters for T&M controls. Across 2.2M+ quote line items in Level benchmark research (all job types, not a T&M-only cut), quoted labor carries a 47.7% gross margin and quoted materials 31.5%. The quoted line-type margin figures are reported in the Level benchmark file as medians across line items, not dollar-weighted margins. They differ, but do not establish a realized ranking for every billed labor or materials dollar.
Fictional arithmetic at those quote-line margins: $150 of billed labor contributes about $71.55 of gross profit ($150 × 47.7%), and $150 of billed materials contributes about $47.25 ($150 × 31.5%). Per dollar, that is roughly 1.5 times as much for labor. That comparison is about pricing and mix. It is not the cost of a leak. Once the technician has been paid or the part has been bought, an unbilled $150 hour or an unbilled $150 part removes the full $150 from both revenue and gross profit, because the cost is already in the job.
Both matter. Start your controls where your own billing-capture and parts-reconciliation audit shows the larger dollar leak. Labor time is often the harder one to reconstruct, because several people record it across a day and it is difficult to rebuild after the invoice goes out.
The Bottom Line
T&M work is where reviews most often find unbounded scope and gaps between estimated and actual cost, though Level has not published a T&M-specific margin comparison. In one individual review, fewer than one in ten quote records were marked as sent, which does not establish communication or approval through other channels. Across all job types in Level's labor-hours data, 40% of jobs exceed their labor budget. One reviewed service visit also grew far beyond its small quote without documented customer notification. The company figures stay qualitative.
The controls aren't complicated: send estimates, set scope boundaries, trigger alerts at 80% of budget, validate time daily, and review every job over $5K after completion. These controls give every T&M job a documented boundary and an early warning. Without them, the shop absorbs scope creep it never priced.
Q: How does Level help with T&M controls? A: We set up budget-to-actual tracking by job where your QuickBooks edition and field-service software support it, or through a reviewed report or export where they do not. We set alert thresholds for cost overruns and review T&M job profitability in your monthly financial package. Confirm which systems can be connected directly during scoping. For contractors with high T&M volume, we compare estimate accuracy, billing capture, and scope-change controls with the relevant Level benchmark definitions. The first audit is free.
Q: Should I switch all my T&M work to flat rate? A: Not necessarily. The issue isn't the pricing model, it's the controls around it. T&M with good controls (sent estimates, scope approval process, budget alerts) can be highly profitable. T&M without controls is a margin black hole. Fix the controls first, then evaluate whether specific job types would benefit from a flat-rate model based on your historical cost data.
Q: What's a good billing-capture target for T&M work? A: The measured median is 97.1% of hours invoiced divided by hours logged on jobs, and the lower quartile is 89.2%, across 963 companies. Start by reconciling job time to invoice lines and legitimate write-offs. Travel, administration, training, and idle time belong in a separate paid-hour-utilization calculation unless they were logged to the job.
Q: How does T&M scope creep relate to budget overruns? A: T&M and fixed-price jobs can overrun for different reasons. T&M risk often comes from unbounded scope without customer visibility, while fixed-price risk often comes from estimate error or uncaptured changes. In Level's labor-hours dataset, which covers all job types rather than T&M alone, the median measured job lands at 99.4% of budget, 40% exceed budget, and 18.3% exceed 150% of budget. Change orders are the formal mechanism for customer-approved scope changes before they become margin leaks.
Source and claim note
Labor-hours-versus-budget (all job types) and billing-capture values come from Level's downloadable contractor benchmark data. Quote-line margins by cost type (labor 47.7%, materials 31.5%) come from Level benchmark research across 2.2M+ quote line items. The sent-estimate documentation observation and the service-visit invoice expansion are individual review observations, kept qualitative; they are not market prevalence estimates and the underlying records are not published. Dollar impacts and control thresholds are operating scenarios that should be recalculated using the shop's own job hours, rate card, contract terms, and approval policy.
Get the next one
Want next week's benchmark in your inbox?
One email a week. Real numbers from 2,200+ service businesses. No fluff. Unsubscribe anytime.
Related reads
Job Costing
Contractor Finance KPIs Ranked by Profit Impact (2026)
The 8 financial KPIs that move a contractor's bottom line, in an editorial priority order by profit leverage, with Level Index benchmarks where a measured sample exists and measurement steps where one does not.
Job Costing
Your 45% Job Could Really Be a 24% Job. Here's Where the Margin Goes.
In a fictional illustration, a contractor job bid at 45% gross margin lands between about 24% and 29% once labor is fully burdened, callbacks counted, material drift priced, and AR financing charged. Rebuild it with your own numbers.
Job Costing
Landscaping Route Margin: Rebuild Labor Cost Correctly
Rebuild landscaping route margin using loaded labor, drive time, equipment per crew-hour, and seasonal capacity. Includes Level job-data context.
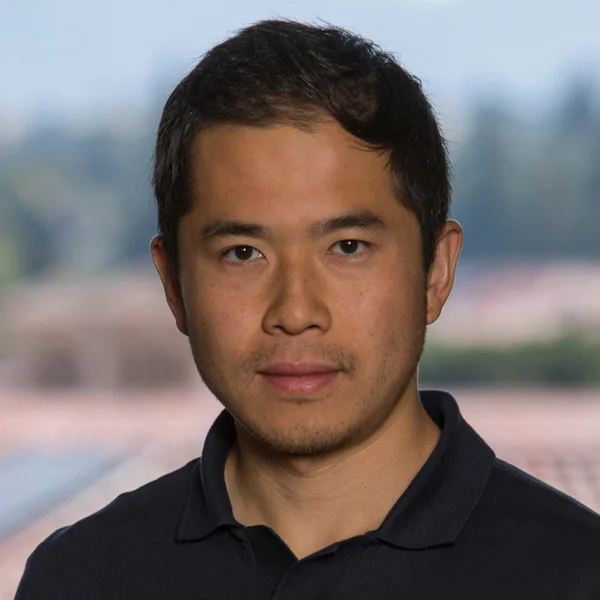
About the author
Sam Yang
Founder & CEO
Founder of Level, the AI operating layer for contractors and skilled trades, and the other operating businesses where scarce labor is the constraint. Ex-CFO across trades, SaaS, and service businesses. 4 years as Director of Growth Product at BuildOps, building financial tooling used by 1,000+ commercial contractors. Four years in PE and investment banking rolling up and acquiring service businesses, $2.5B in total transactions including M&A and IPOs. Stanford MBA, Brown undergrad. The Level founding team's analysis of 2,200+ contractors ($13.25B in job revenue) across operating, private-equity, and CFO roles anchors the Level Index benchmark research.
LinkedIn